At Thanksgiving dinner, my parents looked at me and said, “Your job is to work while your brother enjoys his life. If you don’t like it, there’s the door.”
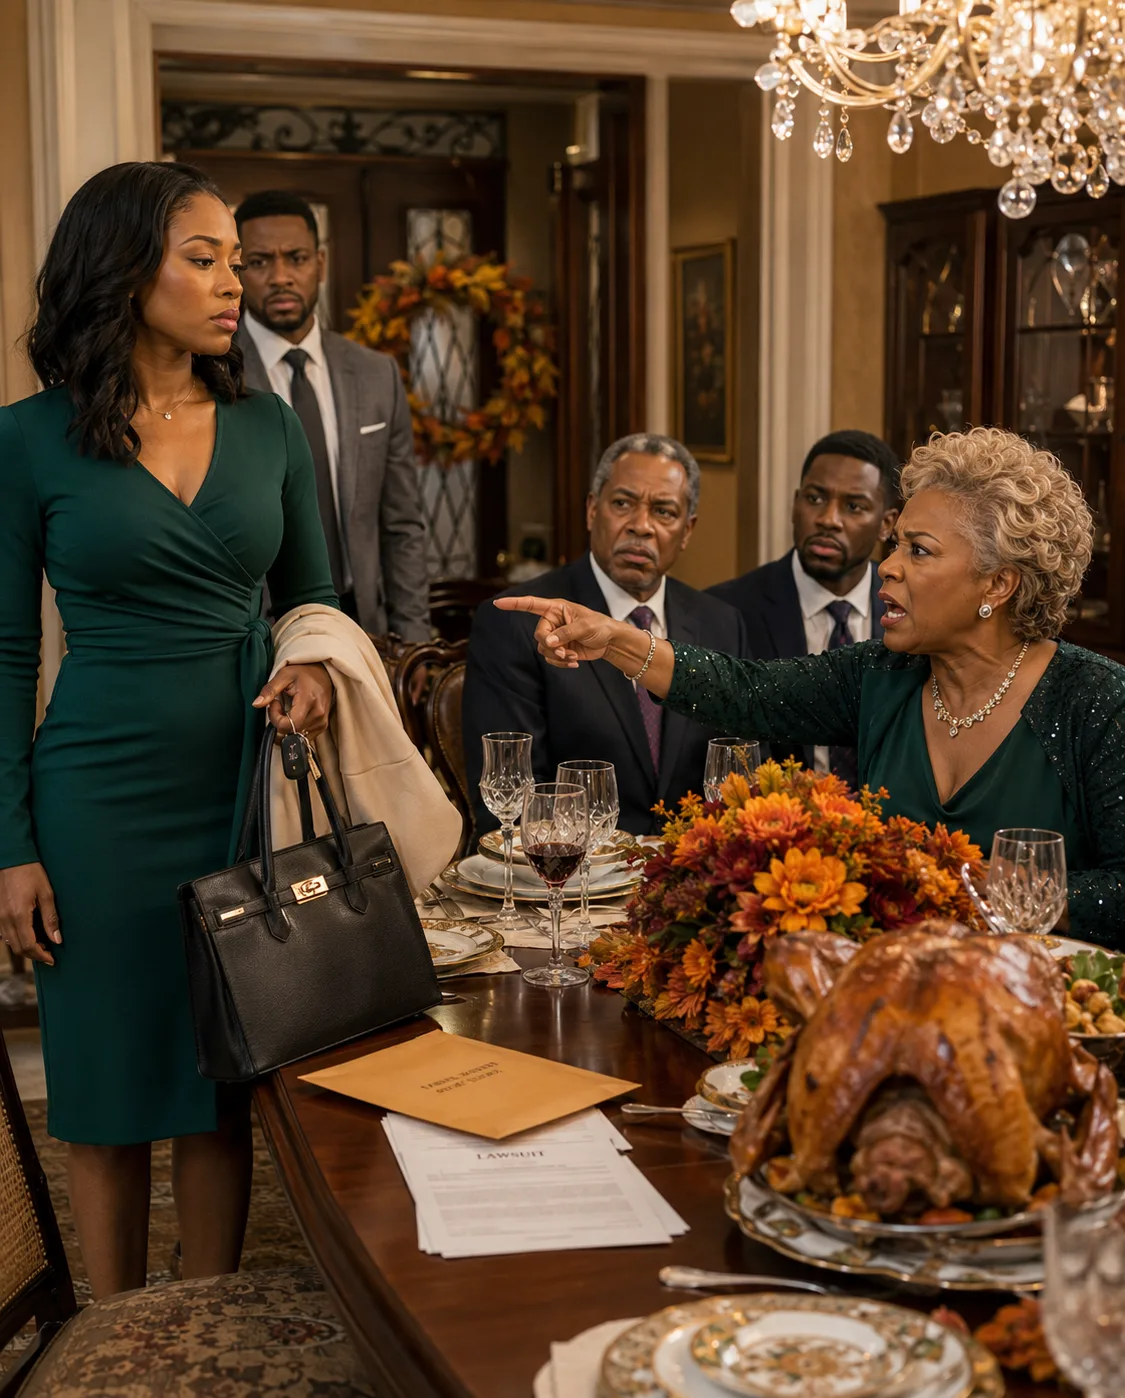
My mother pointed toward the hallway.
“If you don’t like it, there’s the door.”
I looked at her hand.
Perfect manicure.
Diamond bracelet.
The bracelet had been Dad’s anniversary gift.
The credit-card payment that month had come from me.
She did not know I knew.
Or perhaps she knew and had stopped thinking about it.
That was the problem.
My money had become invisible.
Thanksgiving dinner continued to steam between us.
Turkey.
Stuffing.
Sweet potatoes.
Green beans.
Crystal glasses.
Linen napkins.
Everything looked expensive and calm.
My family was neither.
My name is Claire Whitmore.
I was twenty-nine.
I worked in Manhattan as a portfolio manager for a private wealth firm.
Numbers were my profession.
Risk.
Debt.
Liquidity.
Cash flow.
Concentration.
People paid me to tell them uncomfortable truths before those truths
became expensive.
At home, I had spent years doing opposite.
I knew my family’s numbers did not make sense.
I simply refused to calculate them.
My older brother Daniel sat across from me.
Thirty-three.
Tailored navy jacket.
Expensive watch.
Confidence that had survived more failed companies than most people
survive parking tickets.
Beside me sat my fiancé, Marcus Hale.
Corporate restructuring attorney.
Quiet.
Observant.
Dangerously good at recognizing insolvency disguised as optimism.
Daniel had just asked me for one hundred thousand dollars.
“Seed capital,” he called it.
His newest company sold premium botanical beverages.
Or planned to.
There were no meaningful sales yet.
No signed hotel contracts.
No national distribution.
No institutional investor.
But there was beautiful packaging.
Daniel slid presentation across table.
Matte black cover.
Gold lettering.
VERDANT RESERVE.
I opened first page.
Luxury botanical beverages for elevated hospitality experiences.
I almost smiled.
“What are current revenues?”
Daniel frowned.
“We’re pre-launch.”
“Purchase orders?”
“We have strong interest.”
“Signed?”
“Not yet.”
“Committed outside equity?”
“Several conversations.”
“Term sheets?”
“No.”
“Then what is hundred thousand for?”
“Production.”
“How much inventory?”
“First run.”
“At what unit cost?”
He exhaled.
“This is why nobody likes talking business with you.”
“Because I ask numbers?”
“Because everything becomes audit.”
“You are asking me for six figures.”
Mom set down wine.
“Claire.”
“Yes?”
“Your investments have done extremely well this year.”
I turned slowly.
“How would you know?”
“The market is public.”
“My accounts aren’t.”
She waved hand.
“You work in finance.”
“You could sell small portion Monday and barely notice.”
Marcus put fork down.
Not dramatically.
Just enough for me to notice.
He would not intervene unless I wanted him to.
I said:
“I’m not liquidating investments.”
“And I’m not investing hundred thousand in Daniel’s company.”
Mom’s face tightened.
“You haven’t read proposal.”
“I asked basic questions.”
Daniel leaned back.
“You always think you’re smartest person in room.”
“No.”
“I think investor should know where money goes.”
Dad stopped carving turkey.
“Your brother deserves real chance.”
“He has had real chances.”
“That isn’t supportive.”
I looked at him.
“Who paid vendor balance after his last company closed?”
Silence.
Dad looked down.
I knew answer.
Me.
Not directly.
That was how family disguised pattern.
Daniel’s fitness subscription company collapsed.
Parents called.
“We helped him settle a few things.”
“We’re temporarily short.”
“Could you cover property taxes?”
I did.
Then Dad’s card minimum.
Then roof.
Then insurance premium.
Then country club assessment.
Mom called that one embarrassing.
“We have known these people thirty years.”
“We can’t suddenly miss assessment.”
I sent money.
Every emergency temporary.
Every payment exceptional.
Five years later, exceptional had become operating model.
Mom said:
“Daniel is creative one.”
“And?”
“You have stability.”
“Yes.”
“Reliable income.”
“Yes.”
“You don’t have children yet.”
Marcus’s jaw tightened.
“You have flexibility.”
I knew sentence before she finished.
“Your brother is trying to build something.”
“So?”
“Your job is to work so he can have freedom to reach his potential.”
Silence.
Even Daniel looked uncomfortable.
I stared at Mom.
“Say that again.”
“You heard me.”
“My job is to work so Daniel can enjoy freedom?”
“I didn’t say enjoy.”
“You said reach potential.”
“Same financial result.”
“You’re twisting words.”
“I’m repeating arrangement.”
Dad said nothing.
That hurt.
Daniel finally spoke.
“Nobody is forcing you.”
I looked at him.
“You asked for hundred thousand while Mom explains financing you is my
family role.”
“You’re being dramatic.”
“No.”
“I think this is first unusually clear conversation we’ve had.”
Mom’s cheeks reddened.
“If supporting your own brother is such problem, maybe stop pretending
you care about family.”
Then finger toward hallway.
“If you don’t like it, there’s door.”
There it was.
The old threat.
Belonging.
As children, Daniel and I learned different rules.
Daniel could fail and remain loved.
I could disagree and risk exile.
Maybe not literal exile.
But coldness.
Silent treatment.
Canceled invitations.
Comments.
Mom saying:
“We thought you’d rather work.”
Dad saying:
“Your mother is upset.”
Daniel saying:
“Why can’t you just let things go?”
The door was always there.
Symbolically.
Behave or stand outside.
For twenty-nine years, it worked.
I looked at doorway.
Then napkin.
I dabbed mouth.
Folded linen beside plate.
Stood.
Marcus stood too.
Dad looked up.
“Claire.”
“Fine.”
Mom blinked.
“I’ll take door.”
I put handbag over shoulder.
Then:
“And starting tomorrow, you can pay your own bills.”
Nobody moved.
Mom’s face changed first.
“What does that mean?”
“It means what it sounds like.”
“The property taxes?”
“Yours.”
Dad’s chair shifted.
“The cards?”
“Yours.”
“The club assessment?”
“Yours.”
Daniel laughed once.
“You’re really doing this because I asked for investment?”
“No.”
I looked at him.
“I’m doing this because Mom finally explained arrangement clearly enough
that I stopped pretending it was temporary.”
Marcus opened front door.
Cold November air entered foyer.
I walked out.
Nobody followed.
In car, I shook.
Marcus did not start engine immediately.
“You okay?”
“No.”
“Want to go back?”
“No.”
“Want me to say something useful?”
“No.”
“Excellent.”
I laughed despite myself.
He started car.
We drove toward Manhattan.
Halfway home, I cried.
Not because I regretted leaving.
Because part of me still expected Mom to call.
Come back.
We didn’t mean it.
You belong here.
Phone stayed dark.
Next morning, Manhattan was bright and freezing.
I stood at kitchen island with black coffee.
Marcus opened laptop.
“You still want to do this?”
“Yes.”
“Then correctly.”
That mattered.
There was no giant red button labeled:
STOP FUNDING FAMILY.
Financial relationships are messy.
Some payments were voluntary.
Some recurring.
Some attached to accounts in my name.
Some reimbursements.
Some arrangements I needed to review before touching.
Marcus said:
“First principle.”
“What?”
“Do not interfere with obligations that aren’t yours.”
“I know.”
“Second.”
“Don’t move anyone else’s money.”
“I know.”
“Third.”
“Document.”
I smiled.
“Now you sound like me.”
“Terrifying.”
I opened spreadsheet.
Property taxes.
I had voluntarily scheduled payments from my account.
Canceled future payment.
Credit cards.
Cards belonged to parents.
I was not account owner.
I had simply been making online payments from my bank.
Stopped.
Country club.
Their membership.
My card had been stored for certain assessments.
Removed my payment method after confirming I had authority to remove my
own card.
Streaming subscriptions.
Wine club.
Landscaping supplement.
Cell-phone family add-on I had been reimbursing.
Stopped what was mine.
Not what was theirs.
By 9:30:
Payment canceled.
Autopay removed.
Card deleted.
Recurring transfer stopped.
No dramatic music.
Just confirmations.
At 1:17, Dad called.
“Your mother says tax payment was canceled.”
“Yes.”
“We built budget around that.”
I closed eyes.
Their budget.
Built around my money.
“Then budget needs change.”
“You’ve paid it three years.”
“I know.”
“Why suddenly?”
“Not suddenly.”
“Feels sudden.”
“Because you treated temporary support as permanent income.”
He sighed.
“Your mother is very upset.”
“I’m sure.”
“Can we talk after weekend?”
“We are talking.”
“I mean calmly.”
“I am calm.”
That bothered him.
Anger could be dismissed.
Calm required content.
He said:
“Daniel’s business request was separate.”
“No.”
“How?”
“Your household needs my money because your money keeps going to
Daniel.”
“That is not fair.”
“Then show me numbers.”
Silence.
I waited.
“Dad?”
“We’ll talk.”
He hung up.
Mom called ten minutes later.
Voicemail.
“Claire, this is unbelievably vindictive.”
I deleted nothing.
Saved voicemail.
Not for lawsuit.
For memory.
Because family conversations had strange way of being rewritten later.
Daniel called.
“Happy now?”
“No.”
“My business line is under review.”
“That has nothing to do with me stopping Mom’s property taxes.”
“You told lender you won’t renew support.”
I paused.
“What support?”
Silence.
He realized too late.
“What lender?”
“Forget it.”
“No.”
“What lender?”
“It’s routine.”
“Daniel.”
He exhaled.
“Working capital facility.”
“Why would lender expect my support?”
“Old documentation.”
“What documentation?”
“Nothing.”
My body went cold.
“Send it.”
“No.”
“Then give me lender name.”
“Why?”
“Because you just said a lender expects me to renew support.”
“It isn’t big deal.”
“Then send document.”
He hung up.
Marcus was in office.
I called.
He answered:
“What happened?”
I told him.
He became very quiet.
“Do not call Daniel again.”
“Why?”
“Because we need know what exists before anyone starts improvising.”
“I wasn’t going to threaten him.”
“I know.”
“Email him.”
“What do I say?”
“Something boring.”
I smiled despite fear.
“Your favorite.”
We drafted:
Daniel,
During our call today, you stated that a lender was reviewing a business
facility because I had declined to renew financial support.
I do not recall agreeing to guarantee or support current obligations of
your company.
Please provide copies of any documents or representations supplied to
lenders that reference me, my assets, my income, or my financial
support.
Do not use my name or financial information in connection with any new
financing without my written authorization.
Claire
Sent.
No response.
Two weeks passed.
Nothing spectacular happened.
Parents canceled club dining.
Mom stopped housekeeper one day per week.
Dad mentioned selling second car.
Daniel delayed production.
Nobody lost house.
Nobody starved.
World continued.
That surprised emotional part of me.
I had been trained to believe my no would create catastrophe.
It created budgeting.
Then email arrived.
Property-record alert.
I had set alerts years earlier after helping parents review title fraud
protections.
NEW FILING RECORDED.
Their Connecticut address.
I opened public record.
Home-equity line.
Recorded months earlier.
Maximum principal:
$225,000.
I sat.
Read again.
Borrower names:
Richard Whitmore.
Elaine Whitmore.
Their house.
Their signatures.
Nothing inherently improper.
Homeowners can borrow against equity.
But purpose notation and timing worried me.
I called Dad.
No answer.
Mom.
No answer.
Next morning Dad called.
“What did you find?”
Not:
What are you talking about?
He knew.
“The equity line.”
Silence.
“How much went to Daniel?”
“Claire.”
“How much?”
“Two hundred.”
“Two hundred thousand?”
“Yes.”
I closed eyes.
“You borrowed against house for him?”
“It wasn’t supposed to be permanent.”
“Was it loan to him?”
“Yes.”
“Written promissory note?”
Pause.
“Not exactly.”
“Equity?”
“He said we’d get ownership.”
“Documents?”
“We have emails.”
“Attorney review?”
“No.”
“Accountant review projections?”
“No.”
“We trust our son.”
“When was last HELOC payment?”
Silence.
“Dad.”
“Last month.”
“Who paid?”
“I did.”
“With what?”
“Checking.”
“Which checking?”
He did not answer.
I knew they had retirement income.
Some investments.
But household spending was high.
I had been covering gaps.
Now debt service too.
“How much cash remains?”
“Claire, I don’t want interrogation.”
“This is why you called me difficult at Thanksgiving.”
“Because I ask questions after you borrow two hundred thousand against
house.”
He sighed.
“We made decision.”
“Yes.”
“And it is your decision.”
“Then why were you expecting me to keep paying taxes and cards?”
Silence.
That was answer.
They had transferred risk.
Their house supported Daniel.
My income supported them.
A chain.
I printed lien record.
Then opened old folder.
Daniel’s previous businesses.
I had kept documents because finance people keep everything.
Three years earlier, Daniel needed small commercial lease.
Landlord wanted evidence of support.
Parents asked if I would provide letter stating I could assist with
limited initial deposit if needed.
I had agreed to narrow letter.
Not guarantee.
Not open-ended support.
I found copy.
One page.
Specific lease.
Specific maximum amount:
$15,000.
Expiration date.
No continuing obligation.
My signature.
I scanned.
Then Daniel finally replied.
Attached PDF.
“Here. This is what I meant. It’s old.”
I opened.
My stomach dropped.
Letterhead looked similar.
My name.
My professional title.
Signature image.
But language different.
“To whom it may concern…”
It described me as financially supporting Daniel’s ventures.
It stated intention to provide liquidity support for obligations if
necessary.
No $15,000 cap.
No specific lease.
No clear expiration.
My signature appeared at bottom.
I whispered:
“No.”
Marcus read over shoulder.
His face changed.
“Did you sign this version?”
“No.”
“Are you certain?”
“Yes.”
“Do you have original?”
I pointed.
He compared.
“Do not accuse Daniel of forgery yet.”
“Marcus.”
“I know what it looks like.”
“It has my signature.”
“I know.”
“Language changed.”
“I know.”
“Then what else—”
“Documents can be altered by multiple people.”
“Versions can be mislabeled.”
“Signature images can be reused.”
“Lenders may have received something through intermediary.”
“We establish chain.”
I hated lawyer brain.
Because correct.
“What do we do?”
“Your personal lawyer.”
“You are lawyer.”
“I am your fiancé.”
“And restructuring counsel.”
“Which is why I am telling you to hire independent counsel.”
He recommended attorney.
Nina Patel.
Commercial litigation and financial fraud.
She reviewed documents.
First instruction:
“Freeze assumptions.”
Second:
“Preserve everything.”
Third:
“Notify lender accurately and narrowly.”
We identified lender from document package.
Regional commercial bank.
Nina drafted notice.
I did not authorize current guarantee or continuing support.
I disputed any representation otherwise.
Requested copies of documents bearing my name.
Asked bank to preserve communications and application records.
No accusations.
No threats.
Bank responded quickly.
Facility was not fully guaranteed by me.
That was relief.
But my purported support letter had been included in underwriting
materials.
Important distinction.
A support letter is not automatically enforceable guarantee.
Wording matters.
Reliance matters.
Authority matters.
Still serious.
Bank placed pending renewal under review.
Daniel exploded.
“You killed company.”
“No.”
“You contacted bank.”
“Because bank had document using my name.”
“You signed it.”
“I signed different letter years ago.”
“Same thing.”
“No.”
“It says you’ll support me.”
“The one I signed did not.”
“You always said you’d help.”
“That is not authorization to alter document.”
“I didn’t alter anything.”
There.
First direct denial.
“Then who did?”
“I don’t know.”
“Who submitted it?”
“My finance consultant.”
“Who gave it to consultant?”
Silence.
“Daniel?”
“Mom had old files.”
My heart sank.
“Mom?”
“She helped assemble package.”
I hung up.
Not because conclusion.
Because rage.
Nina told me not to conduct witness interview myself.
Formal requests followed.
Parents retained counsel.
That made Thanksgiving feel very far away.
Dad called:
“Do we really need lawyers?”
“Yes.”
“This is family.”
“Bank document has my name.”
“We can explain.”
“Then explain through records.”
Mom called crying.
“I never meant to hurt you.”
“What did you do?”
“I don’t know what you’re accusing me of.”
“I am asking.”
“I helped Daniel organize paperwork.”
“Did you edit my letter?”
“No.”
“Did you give him electronic copy?”
“I may have.”
“Did you tell lender I would support him?”
“I said you always help family.”
My stomach turned.
“That is not same as financial commitment.”
“I didn’t know they would interpret it that way.”
“What exactly did you send?”
“I don’t remember.”
“Then stop guessing.”
She cried harder.
Old me would comfort.
I did not.
Investigation was not criminal television drama.
No detective kicked door.
No handcuffs at breakfast.
It was emails.
Document requests.
Metadata review.
Bank records.
Version histories.
Consultant interviews.
Slow.
Technical.
Eventually, clearer picture emerged.
Years earlier, my limited support letter existed as editable document in
family email chain before final signed PDF.
Mom had retained both.
During Daniel’s later financing effort, an outside finance consultant
requested evidence of family financial backing.
Daniel forwarded materials gathered by Mom.
A revised letter was created using old language and signature image.
Records indicated edits were made from a computer used in Daniel’s
business office.
Who physically typed every word was disputed.
Daniel denied personally altering signature.
Consultant said he believed document had been authorized.
Mom admitted she had told consultant:
“Claire has always stood behind Daniel financially.”
That statement was reckless.
Maybe she believed it emotionally.
Financial institutions do not underwrite emotions.
They underwrite representations.
Bank ultimately concluded it could not rely on disputed support letter.
Renewal terms changed.
Daniel had to find other capital or reduce operations.
No court declared me guarantor.
No lender seized my assets.
That was important.
The danger was stopped because disputed representation was challenged
before becoming something worse.
Parents’ HELOC remained real.
That was their debt.
They had signed it.
They had received proceeds.
They had transferred approximately $200,000 toward Daniel-related
investments and loans.
Those transactions had consequences.
My parents finally sat with independent financial planner.
Not me.
I refused role.
Planner showed them cash flow.
Without my subsidies, they were running monthly deficit.
With HELOC payment, worse.
Their retirement was not destitute.
But lifestyle was unsustainable.
Large house.
Country club.
Frequent travel.
Two luxury vehicles.
Gifts.
Daniel support.
They had confused assets with income.
Classic mistake.
Dad called afterward.
“We have to sell house.”
“Do you?”
“Planner says we could stay if we cut almost everything else and
restructure.”
“What do you want?”
“I don’t know.”
For first time, he asked himself instead of me.
They eventually sold.
Not foreclosure.
Not emergency.
Voluntary sale.
Paid HELOC.
Bought smaller townhouse.
Mom cried for months.
She blamed me at first.
“If you had kept helping—”
I stopped her.
“No.”
“What?”
“If sentence begins with ‘if you had kept paying,’ stop.”
“You abandoned us.”
“No.”
“I stopped subsidizing lifestyle you could not afford while you sent
your capital to Daniel.”
“He is your brother.”
“Yes.”
“And you are adults.”
She hung up.
We did not speak six weeks.
Dad did.
Quietly.
He apologized.
“I thought your success meant you needed less from us.”
“It did not mean I owed more.”
“I know now.”
“Do you?”
“Yes.”
“We built budget around you without asking.”
“Yes.”
“That was wrong.”
“Thank you.”
Then:
“I am sorry about letter.”
“Did you know?”
“I knew your mother told bank you would help.”
“Did you know document was different?”
“No.”
I believed him.
Not because he was Dad.
Because evidence supported limited knowledge.
That distinction became important to me.
Family loyalty should not replace evidence in either direction.
I would not falsely excuse him.
I also would not accuse him beyond facts.
Daniel’s company survived.
Barely.
He cut launch.
Reduced inventory.
Dropped luxury packaging.
Took smaller production run.
Found actual outside investor willing to invest at lower valuation.
Investor demanded board seat and reporting.
Daniel hated it.
Then learned.
His first real investor did not call him genius.
She asked:
Gross margin?
Burn rate?
Customer acquisition cost?
Inventory turns?
Cash runway?
Exactly questions he mocked me for asking.
A year later, he called.
“You were right.”
I almost fell off chair.
“About?”
“Everything becoming audit.”
I laughed.
“What?”
“Turns out investors like audits.”
“They like diligence.”
“Same emotional experience.”
I smiled.
“How’s business?”
“Alive.”
“Good.”
“Not rich.”
“Also good.”
He hesitated.
“I’m sorry.”
“For Thanksgiving?”
“For asking hundred thousand?”
“For letter?”
“All.”
I waited.
He continued.
“I didn’t think of your help as costing you.”
“That was convenient.”
“I know.”
“I thought because you had more, it mattered less.”
“That is not how money works.”
“I know.”
“Or time.”
“I know.”
“Or respect.”
Silence.
“I know.”
That was beginning.
Not repair.
Beginning.
Marcus and I married following fall.
Small wedding.
No mahogany table.
No country club.
Parents came.
Daniel came.
No business pitches.
Mom gave toast.
I was nervous.
She said:
“When Claire was little, I praised her for being independent.”
“I did not understand that sometimes parents praise independent child
because it makes asking less of themselves easier.”
Room quieted.
“She deserved support too.”
“I am learning difference between being proud of someone’s strength and
exploiting it.”
I looked down.
Marcus squeezed hand.
Mom finished:
“I am proud of my daughter.”
No mention Daniel.
No comparison.
Just me.
That mattered.
After wedding, my relationship with parents stabilized.
Not old version.
Better version.
They paid bills.
Dad tracked budget.
Mom left country club.
She complained.
Then discovered local garden group.
Free.
She loved it more.
Their townhouse was smaller.
Easier.
No giant property tax.
No roof crisis.
They traveled less.
Enjoyed more.
Funny.
Lifestyle downgrade became stress upgrade.
Daniel’s beverage company eventually found niche.
Not luxury empire.
Specialty hospitality product.
Profitable modestly.
He paid parents back part of money over years according to formal
agreement created after financial planner insisted.
Not all immediately.
No miracle.
Some earlier contributions were legally investments with risk.
Some were loans.
Documents mattered.
Parents accepted losses on portions they had chosen to risk.
That was painful.
But honest.
I did not reimburse losses.
That was my boundary.
The disputed support-letter matter resolved without me being held
responsible for Daniel’s obligations.
The bank corrected its files.
My attorney retained documentation.
We did not turn it into family spectacle.
No social-media posts.
No revenge campaign.
Just corrected record.
For years, I kept spreadsheet of family payments.
One night, Marcus found me reviewing.
“What are you doing?”
“Adding.”
“Why?”
“I want total.”
“Why?”
I paused.
Because I wanted number large enough to justify anger.
He understood.
“Do you need it?”
“Yes.”
So we calculated.
Five years.
Property taxes.
Credit-card payments.
Repairs.
Insurance.
Club.
Transfers.
Indirect rescue after Daniel ventures.
Total was more than I expected.
Just over $146,000.
I stared.
Marcus said nothing.
“That could have been down payment.”
“Yes.”
“Investment.”
“Yes.”
“Years of retirement contributions.”
“Yes.”
“I let them take it.”
He shook head.
“You gave it.”
“Difference?”
“Yes.”
“You gave under family pressure and incomplete understanding.”
“But many payments were voluntary.”
“Yes.”
“You can acknowledge agency without pretending dynamic was healthy.”
I hated him when wise.
I closed spreadsheet.
Never opened again.
The number mattered once.
Then boundary mattered more.
If I spent rest of life collecting emotional interest on $146,000,
family would still own my attention.
I did not want that.
I also stopped saying:
They stole my money.
Most did not.
I gave.
Sometimes manipulated.
Sometimes guilted.
Sometimes misled about context.
But I authorized many payments.
Truth was complicated.
That complexity gave me power.
If I gave before, I could stop giving now.
No need to rewrite past to change future.
At work, clients often asked:
“How did I get here?”
Debt.
Overspending.
Concentration.
Family loans.
Lifestyle creep.
They wanted villain.
Market.
Advisor.
Spouse.
Children.
Sometimes villain existed.
Often answer was pattern.
Small choices repeated until structure depended on them.
My family was pattern.
One tax bill.
One card.
One emergency.
One failed business.
One Christmas.
One roof.
No single payment destroyed boundary.
Repetition did.
Thanksgiving did not create problem.
It named it.
Your job is to work so your brother can have freedom.
Brutal sentence.
Also gift.
It translated five years of behavior into language impossible to ignore.
I sometimes wonder what would have happened if Mom had phrased it
better.
“Could you please consider helping Daniel?”
Maybe I would have read proposal.
Maybe invested twenty-five thousand.
Maybe continued taxes.
Maybe HELOC grew.
Maybe disputed support letter remained unnoticed until later.
Her cruelty accelerated truth.
That does not make cruelty good.
But consequences can reveal.
At thirty-five, I became partner at firm.
Parents came to celebration.
Dad hugged me.
Mom cried.
Daniel sent flowers.
Card:
Congratulations.
No funding request enclosed.
I laughed so hard assistant asked why.
Years later, Daniel and I sat at Thanksgiving again.
Different house.
Parents’ townhouse.
Smaller table.
No chandelier.
Mom used ordinary napkins.
Daniel’s company had been profitable three consecutive years.
He brought wine.
Paid for it himself.
During dinner his daughter asked:
“Uncle Marcus, what does Aunt Claire do?”
Marcus smiled.
“Ask her.”
I said:
“I help people make decisions about money.”
Daniel added:
“And she asks annoying questions.”
I looked at him.
He raised hands.
“Useful annoying questions.”
His daughter asked:
“Like what?”
I said:
“Where does money come from?”
“Where does it go?”
“What happens if plan is wrong?”
She nodded seriously.
Then asked Daniel:
“Did Aunt Claire ask you those?”
Everyone froze.
Daniel laughed.
“Yes.”
“Did you know answers?”
“No.”
She looked horrified.
“Dad.”
We all laughed.
Even Mom.
Especially Mom.
That moment would have been impossible years earlier.
Humor without humiliation.
Difference matters.
After dinner, Mom and I washed dishes.
She said:
“Do you remember that Thanksgiving?”
“Yes.”
“I wish I could take sentence back.”
“I don’t.”
She looked at me.
“Why?”
“Because I needed hear it.”
“I didn’t mean it exactly that way.”
“I know.”
“But part of you did.”
She nodded.
“Yes.”
“So did Dad.”
“Yes.”
“So did Daniel.”
“Yes.”
“And part of me believed it too.”
She stopped washing.
“What?”
“I thought my value came from being useful.”
Mom looked sad.
“I taught you that.”
“Partly.”
“I’m sorry.”
“I know.”
We continued dishes.
No dramatic embrace.
Some truths do not need performance.
At doorway later, Mom handed me leftovers.
I took them.
She said:
“Drive safe.”
No request.
No bill.
No emergency.
Just leftovers.
I drove home with Marcus.
Snow began lightly.
He asked:
“You happy?”
“Yes.”
“With family?”
I thought.
“Yes.”
“Because they changed?”
“Partly.”
“And?”
“Because I stopped requiring them to change before I allowed myself
boundaries.”
He smiled.
“Very therapist.”
“Expensive therapist.”
“Worth it?”
“Unfortunately.”
He laughed.
The original Thanksgiving story became family shorthand.
Whenever Daniel starts enthusiastic pitch, Dad asks:
“Does Claire need to fund freedom?”
Daniel groans.
“No.”
Mom says:
“Good.”
We can joke because nobody is asking me to pay.
That is important.
A boundary becomes real when people adapt behavior, not when they praise
wording.
My parents learned to live within income.
Daniel learned capital has terms.
I learned generosity without limit becomes infrastructure.
And infrastructure is expected to stay on.
Nobody thanks electricity every time light works.
They notice when power stops.
That was me.
For years, family flipped switch.
Claire will handle it.
Then Thanksgiving night, I shut off only circuit that belonged to me.
Not their accounts.
Not their house.
Not Daniel’s company.
My money.
My labor.
My automatic yes.
The silence at table was not because I threatened them.
It was because everyone suddenly understood what had been running in
background.
The next morning, I did not destroy their lives.
I removed subsidy.
What happened afterward was accounting.
Their lifestyle shrank.
Their debt became visible.
Daniel’s financing became honest.
My name came off obligations I had not authorized.
Parents sold house voluntarily.
Relationships strained.
Then rebuilt.
Slowly.
Legally.
Financially.
Emotionally.
That is less cinematic than revenge.
It is also stronger.
If I had written giant check to save everyone again, Thanksgiving would
have repeated.
Different year.
Different business.
Same table.
Instead, I took door.
And discovered something strange.
Outside door was not exile.
It was adulthood.
Family still existed.
They called.
They got angry.
They adapted.
Some apologized.
Some resisted.
Nobody vanished because I stopped paying.
That was fear that had controlled me.
If I am not useful, will I still belong?
Answer took years.
Yes.
But even if answer had been no, I could not keep purchasing belonging
forever.
Belonging bought with endless rescue is not belonging.
It is subscription.
And I finally canceled mine.
Not love.
Not family.
The subscription.
Years later, I still work hard.
Daniel still dreams.
Parents still worry.
Mom still occasionally hints instead of asks.
Dad still hates discussing money.
Marcus still tells me when I am trying to solve problem nobody assigned
me.
We are not transformed into perfect people.
We are simply more honest.
That is enough.
At Thanksgiving now, when someone says:
“Can you help?”
I ask:
“With what?”
Then I decide.
Sometimes yes.
Sometimes no.
Nobody points toward door anymore.
May you like
And if they did?
I know where it leads.