Forty-Eight Minutes After My Divorce Became Final, I Disabled My Former Mother-in-Law’s Eight Corporate Cards. She Was Standing in a Marble Sales Office, Preparing to Buy My Sister-in-Law a $4.8 Million Mansion. Every Card Declined.
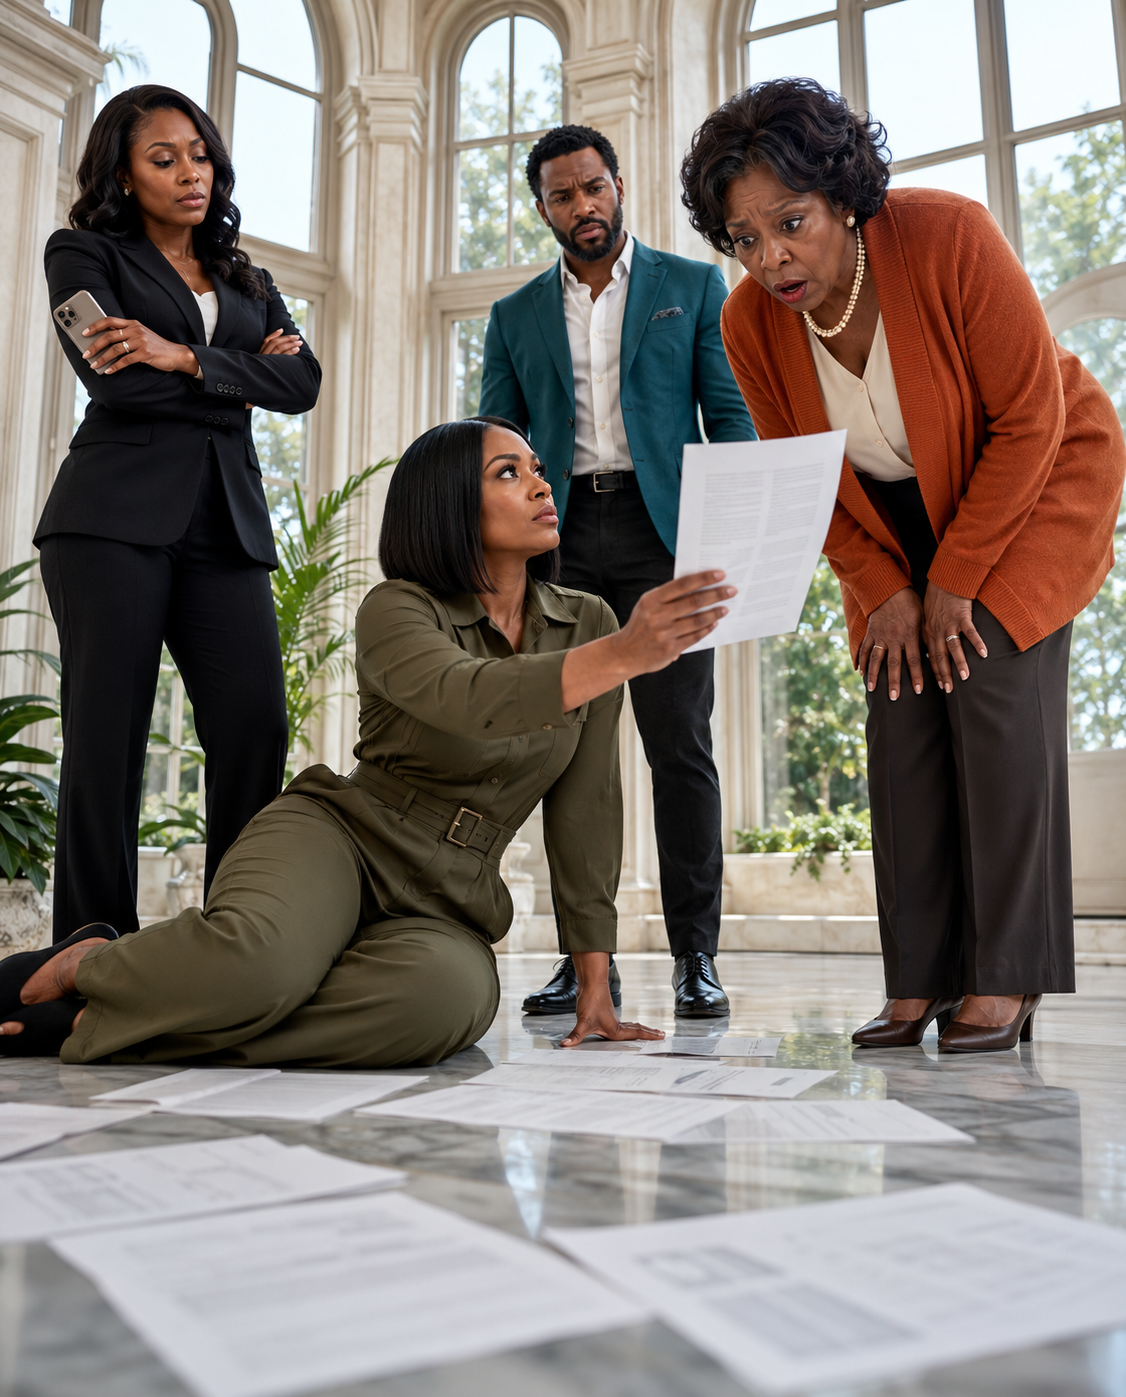
The Eight Cards I Disabled After the Divorce
The divorce decree was finalized at 9:12 on a chilly Tuesday morning in Philadelphia, Pennsylvania.
By 9:40, I had disabled all eight bank cards connected to the Dalton Family Holdings account.
Throughout our marriage, my former husband, Eric Dalton, kept insisting that his mother, Patricia, “managed the family finances.”
That was the story they preferred. It was never true.
Patricia spent the money. I built the system that controlled it.
For seven years, I served as the chief financial officer of Eric’s construction firm, Dalton Urban Development. I designed the financial safeguards, negotiated the credit facilities, and personally backed two emergency loans when the business nearly failed during the pandemic.
In return, Eric had an affair with his marketing director and attempted to push me out of the company before filing for divorce.
He overlooked the one detail that mattered.
The corporate cards still operated under an account requiring my approval for any transaction exceeding fifty thousand dollars.
That afternoon, Patricia, Eric, his younger sister Chloe, and three real estate agents met inside a marble-lined sales office in Bryn Mawr. Chloe was preparing to purchase a seven-bedroom mansion listed at $4.8 million. The family had already assured the seller they would send the down payment that same day, along with nearly two hundred thousand dollars for furnishings and closing costs.
At 1:17 p.m., Patricia’s black card was declined.
She reached for the platinum card. Declined.
Then she attempted the business reserve card. Declined.
Within five minutes, all eight cards had failed.
Eric called me first.
“What have you done?” he yelled.
I was seated in my attorney’s office, reviewing the finalized asset schedule. “I enforced the terms of the banking agreement.”
“My mother is standing in front of the seller.”
“Then she should explain why she’s purchasing a mansion with company funds.”
His voice became quieter. “You’re humiliating us.”
“No, Eric. Your accounting practices are humiliating you.”
In the background, I could hear Patricia shouting at a bank representative. Chloe was crying. One of the agents demanded proof of available funds. The seller’s attorney warned they would cancel the transaction and retain the earnest deposit.
Then Eric said the one sentence that confirmed everything.
“You knew this was Chloe’s house.”
I glanced at my attorney, Julia Hayes, and placed the call on speaker.
“With whose money?” I asked.
Silence.
Julia slid a folder across the desk. Inside were copies of transfers Eric believed I had never uncovered: company money routed through Patricia’s accounts, disguised as vendor payments, before being used to support Chloe’s mortgage application.
Eric finally murmured, “Please don’t do this.”
But the safeguard had already done exactly what I designed it to do.
By sunset, the mansion purchase was falling apart, the bank had frozen three connected accounts, and the family that had spent years treating me like hired help realized I still possessed the keys to the financial empire they had quietly taken.
The following morning, Eric arrived at Julia’s office with Patricia and their attorney, Simon Reed. Patricia wore a cream-colored coat, diamond earrings, and the expression of someone walking into a restaurant expecting the manager to apologize.
No apology came. Only records.
Simon placed a leather folder onto the conference table. “Mrs. Dalton believes the card suspension violated the temporary financial restraining order.”
“Former Mrs. Dalton,” I corrected.
Patricia narrowed her eyes. “You always were so petty.”
Julia opened the banking agreement. “The order prevents either spouse from wasting marital assets. It does not require my client to authorize questionable corporate expenditures.”
Eric leaned forward. “Chloe’s purchase was approved months ago.”
“Approved by whom?” Julia asked.
“My family.”
“Your family is not a recognized legal entity.”
Simon attempted to steer the discussion elsewhere, but Julia had already connected her laptop to the wall monitor. A spreadsheet appeared, displaying payments to companies with names like North Shore Stoneworks, Lakeview Consulting, and Elm Street Logistics.
I had assembled the spreadsheet during the final three months of my marriage after noticing several vendors had no offices, no employees, and identical mailing addresses. Every trail led to a private mailbox rented by Patricia’s personal assistant.
Over four years, $2.3 million had been diverted from Dalton Urban Development.
Chloe’s mansion was simply the latest acquisition.
Patricia stared at the screen. “Those were reimbursements.”
“For what?” I asked.
“For family expenses.”
“Corporate money is not a family allowance.”
Eric’s face flushed. He had always believed confidence could substitute for evidence. “You signed some of those checks.”
“I approved payments backed by invoices. Those invoices were fraudulent.”
That was the moment Simon stopped arguing and began documenting his own clients.
Julia displayed the mortgage application next. Chloe had reported annual earnings of $640,000 from a consulting company that existed only on paper. The application identified Eric’s company as her primary client and included forged verification letters carrying my digital signature.
Eric turned toward his mother.
Patricia did not return the look.
I understood the arrangement then. Eric knew they were draining the company, but he had not known every method Patricia was using. She had treated her own son like just another account she could manipulate.
Simon requested a private recess. Julia declined.
“The seller has filed notice that Chloe’s earnest deposit will be retained,” she said. “The lender has suspended the application. The bank’s fraud department has also requested the original corporate records.”
Patricia’s composure finally broke. “You contacted the bank.”
“I answered the questions they asked.”
“You are tearing this family apart.”
I let out a quiet laugh. “You used my credit, my signatures, and my work to finance your family. You tore it apart yourselves.”
Eric reached across the table and reached for my hand. I quietly pulled it back.
“Natalie,” he said, his voice suddenly calm, “we can still fix this. Reactivate the cards, tell the bank there was a misunderstanding, and I’ll increase your divorce settlement.”
Julia lifted an eyebrow.
“How much?” I asked.
Eric looked visibly encouraged. “Another half million.”
I allowed the silence to linger.
Then I placed a printed email in front of him. It was a message he had sent to Patricia six weeks earlier:
Once the divorce is final, Natalie loses access. Close Chloe’s house immediately after.
The confidence left Eric’s face.
“You intended to leave me responsible for the loan guarantees,” I said, “while transferring the liquid assets through your mother. You expected me to carry the debt after you drained the company.”
Patricia stood so abruptly that her chair slammed into the wall. “This meeting is over.”
“No,” Simon replied.
It was the first occasion he had openly disagreed with her.
He turned toward Eric. “Do not transfer money, contact the bank, or destroy any documents. From this moment on, assume every communication could be reviewed by a judge or a federal investigator.”
Patricia stared at him in stunned disbelief.
Outside the office, Chloe waited near the elevators. She hurried toward her mother, mascara running down her cheeks.
“The seller kept the deposit,” she cried. “And the lender says I committed fraud.”
Patricia pointed directly at me. “She caused this.”
Chloe looked at the documents in my hands, then at Eric’s pale expression.
For the first time, Chloe looked at the documents instead of accepting her mother’s version.
Three days later, the bank assigned an independent forensic accountant. His name was Aaron Blake, a former federal investigator with a soft voice and an unsettling habit of remaining silent after people answered, as though the pause itself might encourage them to reveal something else.
He started with the eight blocked cards.
Four were issued in Patricia’s name, two belonged to Eric, one to Chloe, and one had been assigned to Patricia’s personal assistant, Denise Ward.
Every card had been issued as a corporate expense card.
None carried legitimate spending limits high enough to purchase real estate, but Patricia had discovered how to break large expenses into smaller transactions, temporary authorizations, cashier’s checks, and vendor refunds.
The mansion purchase was intended to follow the same pattern. A shell company would bill Dalton Urban Development for “architectural materials.” The company would pay the invoice. Patricia’s contact inside the shell company would return most of the funds to an account used for Chloe’s closing. The cards were meant to cover furniture, legal fees, taxes, and any expenses the lender questioned.
Blocking the cards had done more than humiliate the family in a sales office. It had stopped the transaction while every dollar remained traceable.
Aaron interviewed me first.
I handed over everything: invoices, emails, bank statements, login histories, and copies of the internal reports Eric had instructed me to revise. I also gave him a small black notebook I had kept in my desk for two years. Every time Eric or Patricia requested approval for an unusual payment, I recorded the date, amount, explanation, and everyone present.
“You expected this?” Aaron asked.
“I expected Eric to blame me if the company failed.”
“Did you expect fraud?”
“Not at first.”
He closed the notebook. “Why didn’t you report it sooner?”
It was a fair question, and I disliked my own answer.
“Because I kept believing I could protect the company without ending my marriage.”
Aaron nodded without either sympathy or criticism. “That belief had protected them.”
He was right.
Eric had depended on my loyalty. Patricia had depended on my hesitation. Both believed that because I had spent years cleaning up their mistakes, I would clean up this one as well.
Instead, I met with the company’s two outside investors. Together, they owned thirty-four percent of Dalton Urban Development and had the authority to demand an emergency board meeting if financial misconduct threatened the business. Eric had never taken them seriously because they rarely attended routine meetings.
They attended this one—and they brought counsel.
The meeting was held on Friday in a downtown conference room overlooking the Schuylkill River. Eric sat at the head of the table, though he no longer looked like the person in control. His tie was crooked, his eyes were bloodshot, and his attorney had advised him to speak as little as possible.
Patricia was not invited.
Aaron presented his preliminary findings. At least $2.3 million had been diverted. Another $900,000 in questionable invoices required further investigation. Several documents contained forged signatures. The company’s credit facility could be suspended unless leadership changed immediately and the investors approved a recovery plan.
Eric tried to interrupt.
One investor, Teresa Morgan, raised her hand. “You will have an opportunity to respond.”
“I founded this company,” Eric said.
“Your father founded it,” Teresa replied. “Natalie made it financially stable.”
That single sentence struck him harder than any accusation.
The board voted to remove Eric as chief executive while the investigation continued. His shares remained his property, but his authority over accounts, employees, contracts, and records ended immediately. In a second vote, I was appointed interim chief restructuring officer.
Eric looked straight at me. “This was your plan from the very beginning.”
“No,” I said. “My plan was to leave you. This became necessary only after I discovered what you had done.”
Security collected his access badge before he walked out.
Patricia called me seventeen times that evening. I ignored every call.
On the eighteenth attempt, she used Chloe’s phone.
I answered because I believed Chloe might actually need help.
Patricia spoke first. “You’ve made your point.”
“I wasn’t trying to make a point.”
“The family is ready to settle.”
“The divorce has already been settled.”
“I’m not referring to the divorce.”
Her tone had shifted. The arrogance had disappeared, replaced by careful calculation. She offered to return certain assets if I convinced the board and the bank to stop their investigations. She mentioned a beach house in Delaware, two investment accounts, and jewelry she claimed had belonged to Eric’s grandmother.
I placed the call on speaker while Julia recorded the conversation. At the beginning of the call, she informed everyone that it was being recorded.
“What about everything else?” I asked.
“There is nothing else.”
“Then we have nothing to discuss.”
Patricia’s breathing became sharper. “Do you think Eric will survive prison? Do you think Chloe will? She signed documents she never understood.”
Chloe’s voice could be heard faintly in the background. “Mom, stop.”
Patricia continued. “You can still save them.”
“No. You can tell the truth.”
The line fell silent.
Then Chloe picked up the phone.
“Natalie,” she said, “did those income letters really have your signature?”
“They contained an image of my signature. I never signed them.”
“I asked Mom where the money came from. She told me it was part of Eric’s ownership distribution.”
“It wasn’t.”
Chloe began crying, but unlike the moment outside Julia’s office, there was no audience and no mansion left to recover. “I believed the company was paying me because the family owned it.”
“You never worked for the company.”
“I know.”
That was the first completely honest thing she had said to me in years.
Chloe agreed to meet Aaron the following morning. Patricia tried to prevent it, but the lender’s fraud notice frightened Chloe more than her mother’s anger.
During the interview, Chloe admitted Patricia had formed the consulting company, filed its paperwork, deposited money into its account, and instructed her to sign the mortgage application without reading it carefully.
Chloe was not blameless. She had accepted luxury vehicles, expensive vacations, and monthly payments without asking questions.
But her cooperation gave investigators direct insight into Patricia’s methods.
Denise Ward cooperated next.
She handed over text messages, voice recordings, and the key to a storage unit. Patricia had stored boxes of original invoices inside a rented unit outside King of Prussia because she did not trust digital records. Denise explained she had followed instructions for years because Patricia paid her son’s college tuition and repeatedly warned the payments would stop if she ever resigned.
The evidence reversed the balance of power.
Within two weeks, the mansion seller sued Chloe for additional losses resulting from the failed closing. The bank closed the family’s personal lines of credit. Eric’s divorce attorney withdrew after discovering Eric had concealed assets during financial disclosure. Julia filed a motion to reopen the settlement based on fraud.
Eric came to my apartment on a Sunday afternoon.
He looked older than he had at the divorce hearing, even though less than two weeks had passed. The doorman called upstairs, and I agreed to meet him in the lobby. I refused to let him into my apartment.
“I didn’t know about the forged signatures,” he said.
“You knew about the transfers.”
“I knew Mom was moving money. She said it lowered taxes.”
“You were the chief executive. You signed the financial statements.”
He lowered his head. “I trusted her.”
“You trusted her when it benefited you. You blamed me when it didn’t.”
He sat in a leather chair beside the window. For several long seconds, neither of us spoke.
“Was any of it real?” he asked.
“Our marriage?”
He nodded.
“For me, it was.”
His expression tightened.
“That’s why this lasted so long,” I continued. “You knew I would protect what we built. You confused love with permanent permission.”
“I can testify against her.”
“That is something you need to discuss with your lawyer.”
“Natalie, please.”
There had once been a time when that single word would have broken me. I would have searched for a solution, softened the consequences, and convinced myself that mercy could restore the man I believed I had married.
Now I saw him for who he truly was. Eric was not asking for forgiveness. He was asking me to become useful again.
I stood up. “This meeting is over.”
He did not follow me.
The criminal investigation continued for nine months. Federal prosecutors eventually charged Patricia with bank fraud, wire fraud, conspiracy, and aggravated identity theft. Eric pleaded guilty to conspiracy and making false statements to a financial institution. His cooperation reduced his sentence, but it did not eliminate it.
Chloe pleaded guilty to a lesser fraud offense and received probation, home confinement, and an order to pay restitution. Denise was not charged.
Patricia rejected every early plea offer. She insisted Eric had orchestrated the scheme and claimed I had manipulated the records after the divorce. At trial, prosecutors presented her messages, the shell-company accounts, Denise’s recordings, and the files recovered from the storage unit.
The most damaging recording captured Patricia laughing after Eric asked whether the transfers could expose him personally.
“He signs whatever Natalie puts in front of him,” Patricia had said. “And Natalie fixes everything.”
The jury returned guilty verdicts on every major charge.
The civil consequences followed almost immediately. Patricia sold her condominium, her lake house, and most of her jewelry to satisfy restitution orders and legal expenses. Chloe moved into a rented two-bedroom apartment and found employment with a property management company. Eric lost voting control after a court-approved sale transferred part of his shares to the outside investors.
Dalton Urban Development survived.
I remained the company’s restructuring officer for eighteen months.
During that time, we recovered insurance proceeds, pursued legal action against two fraudulent vendors, renegotiated the company’s debt, and repaid the emergency loans I had personally guaranteed.
Afterward, I sold most of the shares I received through the reopened divorce settlement.
I kept a small portion.
Not out of revenge, and not because I wanted to stay connected to Eric. I kept it because my work had created much of the company’s value, and I no longer believed that moving on required giving up what I had rightfully earned.
A year after the trial, I received a letter from Patricia in federal prison. It was six pages long. She blamed Eric, Chloe, Denise, the bank, the investors, the prosecutors, and me. She insisted the mansion had always been intended as a family investment. She claimed blocking the cards had created an unnecessary disaster.
I read the letter once.
Then I filed it in the same folder as the first declined-transaction alert.
Patricia was wrong about one thing. Blocking the cards had not created the disaster. It had simply prevented the family from hiding it any longer.
On the second anniversary of my divorce, I stood in the kitchen of a townhouse I had purchased in Media, Pennsylvania. It was modest compared with Chloe’s failed mansion, but every payment came directly from my own account. No shell companies. No forged documents. No family committee pretending personal greed was a business expense.
Julia stopped by that evening carrying a bottle of sparkling cider. She lifted her glass toward the framed company share certificate hanging on my wall.
“To the eight cards,” she said.
I smiled. “To read the fine print.”
My phone buzzed with an automated notification from the bank. Dalton Urban Development had completed the final repayment on the loan I had once guaranteed.
For seven years, the Dalton family treated my competence as though it belonged to them. Eric relied on it to avoid accountability. Patricia used it as a disguise. Chloe enjoyed it as a source of effortless privilege.
The divorce brought that arrangement to an end.
Eight declined cards shattered the illusion.
And when their plans unraveled inside a marble sales office, they believed they had lost a mansion.
May you like
What they truly lost was the woman who had always cleaned up the evidence before anyone else could see the mess.
THE END