My Family Gave Me $5 for My Birthday, Mocked Me, Then Made Me Pay the Dinner Bill—A Year Later, They Begged Me to Save Their House
The first thing my mother said after I told her I would take care of the
mortgage was:
“I knew you wouldn’t let us lose the house.”
I sat at my desk and looked at the folder in front of me.
Years of transfers.
Receipts.
Payment confirmations.
Notes I had made after calls that always began with some version of the
same sentence.
Ryan, we hate to ask.
Ryan, it’s just this once.
Ryan, family helps family.
The total on my spreadsheet was $63,840.
That did not include the birthday dinner.
I had added that separately.
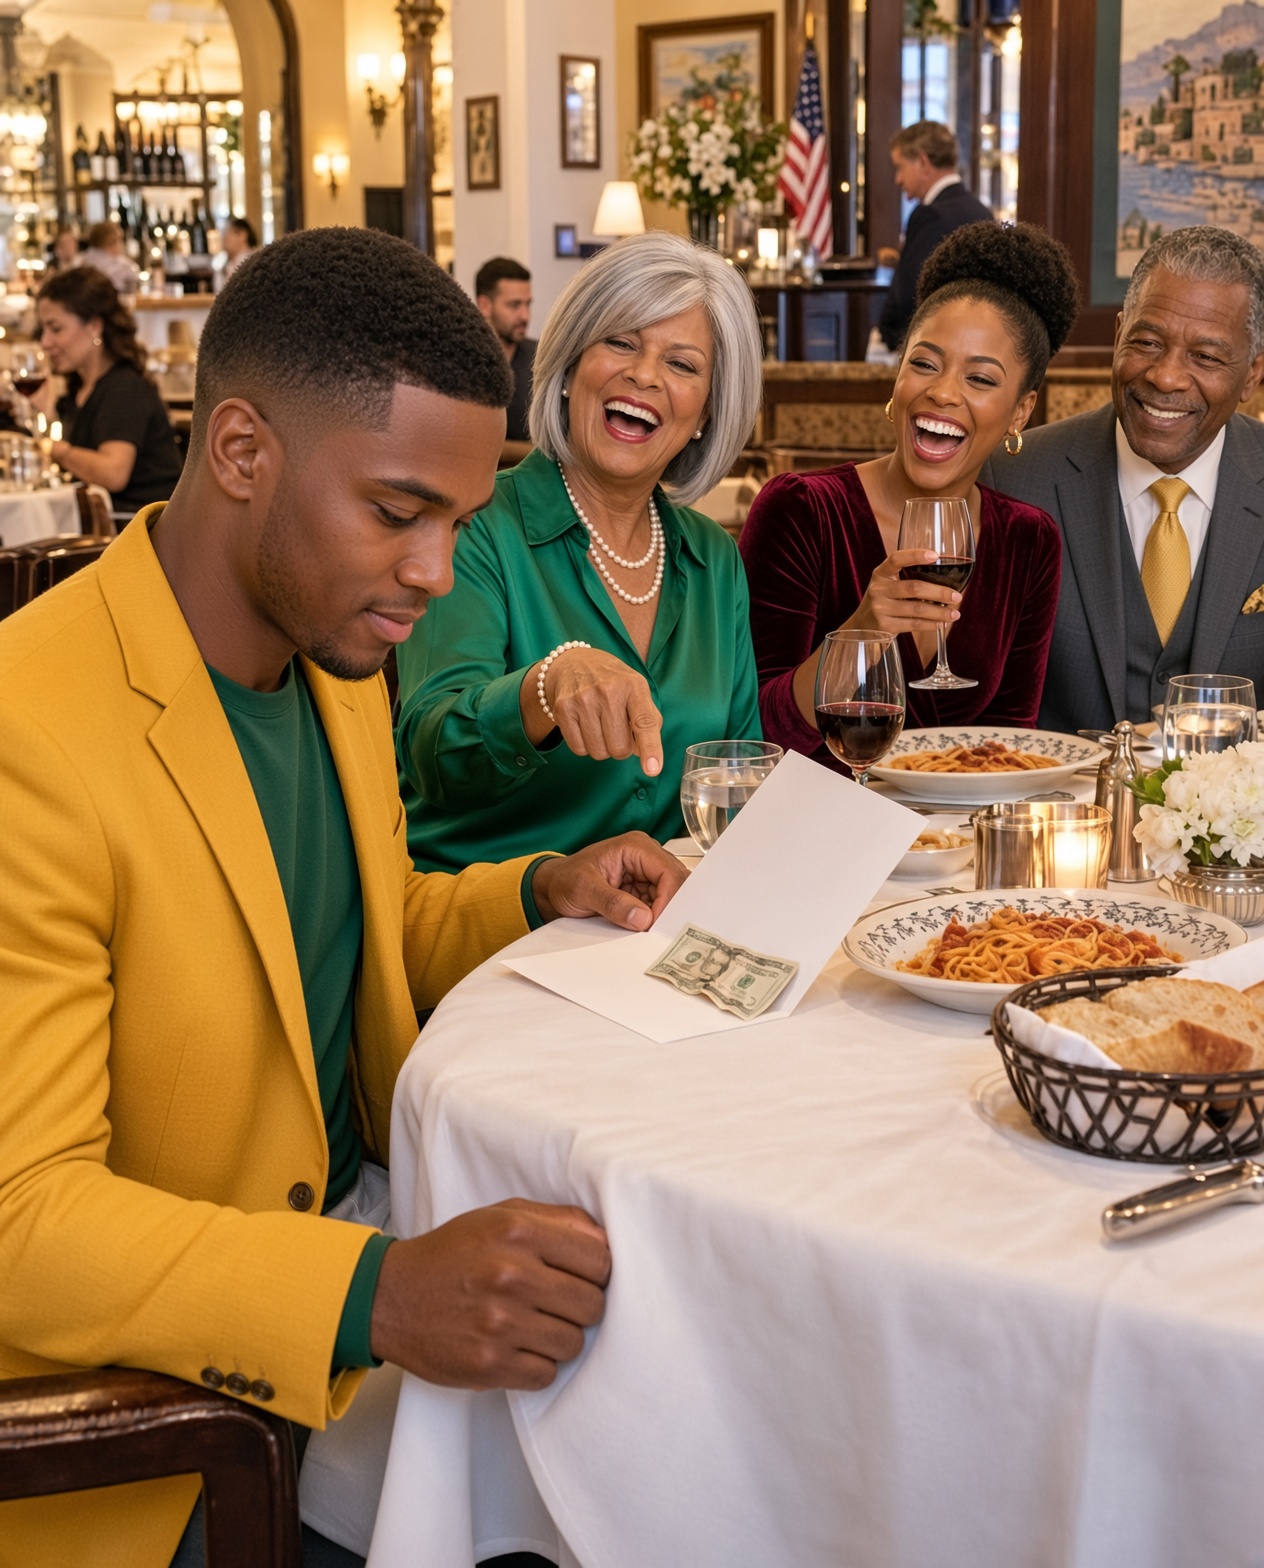
$1,126.43.
Thirty minutes of jokes.
One wrinkled five-dollar bill.
And a restaurant bill handed to me because I was apparently wealthy
enough to fund the people mocking me.
Mom was still talking.
“We can pay you back when things settle down.”
“No.”
She stopped.
“What?”
“Don’t promise that.”
“Why?”
“Because we both know you don’t have a repayment plan.”
Silence.
Then she softened her voice.
“Ryan, your father is scared.”
“I know.”
“So am I.”
“I know.”
“This is the house you grew up in.”
“I know that too.”
Her voice cracked.
“Then you understand.”
I looked at the legal pad beside me.
I did understand.
That was the problem.
For years, understanding had been the door they used to reach my bank
account.
Dad lost a job.
I understood.
Mom had a medical copay.
I understood.
Emily needed help after a breakup.
I understood.
The mortgage was late.
I understood.
Nobody ever seemed interested in understanding what it cost me to be the
person who always understood.
“I’ll call you tomorrow.”
I said.
“Ryan—”
“Tomorrow, Mom.”
I ended the call.
Then I called my attorney.
Her name was Maya Patel.
I had first met her three months earlier after a colleague recommended
her.
I had gone into her office believing I wanted to know whether I could
somehow “take over” my parents’ mortgage if they defaulted.
Maya corrected me quickly.
“You cannot simply assume ownership because you make somebody else’s
mortgage payment.”
She said.
“Real property doesn’t work like a family tab at dinner.”
That sentence probably saved me from doing something foolish.
She explained the difference between paying arrears, lending money,
buying property, acquiring a lender’s interest, and purchasing a home
through a negotiated sale or a lawful foreclosure process.
Every path had different consequences.
Taxes.
Liens.
Title issues.
Loan requirements.
Rights belonging to the current owners.
Rights belonging to the lender.
State procedures.
Nothing happened because I was the responsible son with a spreadsheet.
Documents mattered.
Ownership mattered.
Process mattered.
So when Mom called asking me to “save the house,” I already knew one
thing.
I would not wire money into a mortgage I did not own and could not
control.
Not again.
The next morning, I called Dad.
“What exactly did the bank send you?”
He sighed.
“Letters.”
“What letters?”
“The usual.”
“There is no ‘usual’ when foreclosure is being discussed.”
“You sound like a lawyer.”
“I spoke to one.”
That silenced him.
“Why?”
“Because you told me the house might be lost.”
Dad sounded suspicious.
“What are you planning?”
“Nothing until I see the paperwork.”
“You said you’d take care of it.”
“I said I would.”
“Then make the payment.”
“No.”
His voice hardened.
“Ryan.”
“I’m not sending money until I know the actual situation.”
“We’re your parents.”
“And this is a mortgage.”
Dad breathed heavily into the phone.
Then he said:
“You’ve changed.”
I almost laughed.
“Yes.”
He meant it as an accusation.
I accepted it as a fact.
That evening, Dad emailed me scanned copies of the notices.
The situation was worse than Mom had admitted.
They were not one payment behind.
They were several months delinquent.
There were late fees.
There were other debts.
A home-equity line also appeared in the records.
I called Dad immediately.
“What is the HELOC?”
He went quiet.
“The what?”
“The home-equity line.”
“Oh.”
That one syllable told me he knew.
“How much?”
“I don’t know exactly.”
“The statement says the balance is over forty thousand.”
Mom spoke in the background.
“Don’t start interrogating him.”
I closed my eyes.
“Who borrowed against the house?”
Dad said:
“We did.”
“For what?”
“Expenses.”
“What expenses?”
“Family expenses.”
There was that word again.
Family.
A financial category broad enough to hide almost anything.
I asked for statements.
Dad resisted.
I told him I would not contribute a dollar without complete information.
Two days later, the statements arrived.
I spent Saturday morning reviewing them.
The HELOC had not been used for one emergency.
It had been drawn down repeatedly.
Home repairs.
Credit-card consolidation.
A vehicle.
Several large transfers.
One transfer caught my attention.
$12,000.
Recipient: Emily Carter.
I stared at it.
Then another.
$7,500.
Emily.
Then $4,000.
Emily.
I called Dad.
“Did you borrow against the house to give Emily money?”
“It wasn’t like that.”
“How was it?”
“She needed help.”
“With what?”
“Her business idea.”
“What business?”
Dad hesitated.
“She was going to start a travel consulting company.”
I remembered Spain.
The oceanfront suite.
Emily saying she had worked hard and deserved to enjoy herself.
“Did the company exist?”
“She was planning it.”
“Did she repay you?”
“Not yet.”
“How much did you give her from the HELOC?”
Dad did not answer.
I had already calculated the transfers I could identify.
At least $23,500.
“Did Mom know?”
“Yes.”
“Did you ever ask Emily to help with the mortgage?”
“She has expenses.”
I laughed.
I could not help it.
Dad became angry.
“What’s funny?”
“Nothing.”
“Then stop.”
“You borrowed against your house to help Emily maintain her lifestyle,
and now you want me to save the house.”
“It wasn’t her lifestyle.”
“Then what was it?”
“She was trying to build something.”
“So was I.”
Silence.
I continued.
“For years.”
Dad said nothing.
“I was building savings.”
Nothing.
“A career.”
Nothing.
“A retirement account.”
Nothing.
“And every time I made progress, somebody called because the family
needed money.”
Dad finally said:
“You always had more than she did.”
That sentence explained almost everything.
Not fairness.
Capacity.
If I had ten dollars and Emily had two, my family did not ask why.
They simply decided eight of mine were available.
“I’ll talk to you after I speak with Maya.”
I said.
“Who is Maya?”
“My attorney.”
Dad swore.
I ended the call.
Maya reviewed the documents.
She also ordered a title search with my parents’ authorization after
making clear that we needed to know what encumbered the property.
There were no magical discoveries.
No secret mansion deed with my name on it.
No forgotten trust.
Just a house my parents had owned for twenty-nine years and repeatedly
borrowed against.
The equity was thinner than I expected.
Still meaningful.
But vulnerable.
Maya laid out realistic possibilities.
My parents could pursue available loss-mitigation options with the
lender.
They could attempt to cure the default if they had funds.
They could sell the house before the process advanced further, subject
to timing and lender requirements.
Or, if they truly wanted me to own it, we could explore a legitimate
sale to me at a properly documented price, with independent advice for
everyone involved.
I asked:
“Can I buy it?”
“Possibly.”
She said.
“But not as a revenge trick.”
“I’m not trying to steal it.”
“Good.”
“I’m trying to stop putting money into property while they keep
borrowing against it.”
“Then ownership and control need to match your risk.”
That sentence stayed with me.
Ownership and control need to match your risk.
For years, I had accepted risk without control.
I paid bills I did not create.
Covered loans I did not sign.
Protected a house I did not own.
Financed emergencies I could not prevent.
Then I was mocked for being careful.
I called my parents.
“We need a family meeting.”
Mom sounded relieved.
“Of course.”
“Emily needs to be there.”
The relief disappeared.
“Why?”
“Because some of the home-equity money went to her.”
“That has nothing to do with this.”
“It has everything to do with this.”
“Ryan, don’t punish your sister.”
“I’m not.”
“What do you call dragging her into a mortgage problem?”
“Accounting.”
Mom hung up.
The meeting happened Sunday afternoon.
Same house.
Same living room where I had opened Christmas presents as a child.
Emily arrived twenty minutes late carrying a designer handbag.
I noticed it immediately.
Then hated myself for noticing.
The bag was not the problem.
The problem was what everyone believed the bag represented.
Emily sat.
“This better be important.”
Dad looked exhausted.
Mom looked angry.
I placed copies of the mortgage and HELOC statements on the coffee
table.
Emily glanced at them.
“What is this?”
“The house is in serious default.”
She looked at Dad.
“I thought Ryan was handling it.”
There it was.
I smiled without humor.
“I am.”
“Then why am I here?”
“Because at least $23,500 from the home-equity line went to you.”
Her face changed.
Mom jumped in.
“That was separate.”
“No.”
I said.
“It was borrowed against the same house you now want me to save.”
Emily crossed her arms.
“They gave me that money.”
“I know.”
“So what?”
“So can you repay any of it?”
She stared at me.
“Excuse me?”
“Can you repay any of the money?”
“That’s between me and Mom and Dad.”
Dad looked down.
I turned toward him.
“Do you agree?”
He rubbed his face.
“No.”
Emily’s eyes widened.
Dad continued.
“I need to know what you can repay.”
Mom looked at him.
“Frank.”
“What?”
“You said we weren’t going to pressure her.”
Dad laughed bitterly.
“We’re losing the house.”
Emily stood.
“I cannot believe this.”
I remained seated.
“Why?”
“Because you’re making my finances everybody’s business.”
I almost admired the irony.
“My finances became everybody’s business at my birthday dinner.”
“That was a joke.”
“The five dollars?”
“Yes.”
“The jokes about my clothes?”
“Ryan.”
“The dinner bill?”
Dad interrupted.
“That has nothing to do with this.”
“It has everything to do with why I’m not writing another check.”
Mom’s eyes filled.
“So this is revenge.”
“No.”
I shook my head.
“If it were revenge, I would do nothing.”
The room became quiet.
“I am offering a solution.”
Dad looked at me.
“What solution?”
“You sell me the house.”
Mom stared.
Emily laughed.
I continued.
“Not for five dollars.”
Nobody laughed.
“Maya will help structure it properly.”
I said.
“You get independent counsel.”
“We obtain an appraisal.”
“We account for the mortgage, HELOC, liens, closing costs, and whatever
equity remains.”
“If a sale to me is feasible and the lender requirements can be
satisfied, I buy the property through a normal closing.”
Mom looked horrified.
“You want our house.”
“I want control over the asset you want me to risk my money saving.”
“It’s the family home.”
“It is your home.”
I said.
“And if you want to keep owning it, then pursue the lender’s options and
find a way to fund them.”
Dad stared at the papers.
“What happens if you buy it?”
“That depends on what we agree.”
“You’d throw us out?”
“No.”
I had already thought about this.
“I would offer you a written lease for a defined period at an affordable
rent.”
Mom looked insulted.
“Rent?”
“Yes.”
“To live in our own house?”
“If you sell it, it would no longer be your house.”
She stood.
“This is disgusting.”
“Then don’t do it.”
I said.
That stopped her.
“I’m not forcing you.”
I gathered the papers.
“Talk to the lender.”
“Talk to a housing counselor.”
“Talk to your own attorney.”
“Sell to somebody else if that gives you a better result.”
“But I am not handing over cash with no control and no plan.”
Emily said:
“You’ve been waiting for this.”
I looked at her.
“No.”
“I think you have.”
“You think I spent years paying Mom and Dad’s bills hoping they would
lose their house?”
She had no answer.
I stood.
“My offer is an option.”
I said.
“Not an ultimatum.”
Then I left.
For four days, nobody called.
On Friday, Dad did.
“We want the appraisal.”
That was how it began.
Not with me secretly buying their mortgage.
Not with a bank handing me the keys because I had better credit.
With an appraisal.
Independent advice.
Numbers.
The house was worth less than my parents liked to believe and more than
I had hoped to pay.
There was still equity after the secured debts and costs.
I did not demand they give it to me.
That would have turned their crisis into my opportunity.
We negotiated.
My parents had their own attorney.
I had Maya.
The lender had requirements.
My financing had underwriting.
There were inspections.
There were disclosures.
At one point, the entire transaction nearly collapsed because an old
lien release had not been properly recorded.
Nothing about it felt triumphant.
It felt like buying a house.
Slow.
Expensive.
Administrative.
Real.
Emily repaid $6,000 before closing.
Not the entire amount.
It was what she could produce after selling some investments and
canceling an upcoming trip.
Dad accepted a written repayment agreement for part of the remaining
money.
That was their business.
I did not make Emily’s debt to them a condition of my purchase.
I did insist that no one pretend it had never happened.
Closing took nearly seven weeks.
On the morning it happened, Mom cried.
I expected to feel powerful.
I did not.
I felt sad.
The house was where Dad taught me to ride a bicycle.
Where Mom made pancakes every Sunday.
Where Emily and I once built a blanket fort that stayed up for three
days because our parents did not have the heart to take it down.
A financial boundary did not erase good memories.
Good memories did not erase financial reality.
Both could be true.
At closing, Dad signed last.
Then he put down the pen.
“So it’s yours.”
“Yes.”
He looked at me.
“I never thought we’d sell it to one of our children.”
“Neither did I.”
Mom whispered:
“You really did take care of it.”
I looked at her.
“Yes.”
Just not the way she expected.
The proceeds left after paying the secured debts and closing costs
belonged to my parents.
I did not take them as reimbursement for the $63,840 I had spent over
the years.
Much of that money had been given voluntarily, even if family pressure
complicated the word voluntary.
I had no desire to manufacture a legal debt where none had been
documented.
Instead, my parents used part of their remaining funds to create an
emergency reserve.
At my suggestion, they met with a financial counselor.
At Dad’s insistence, they stopped giving Emily money.
That lasted four months.
Then Mom gave her $500 for a car repair.
Dad was furious.
I stayed out of it.
That was another lesson.
Boundaries are not control.
I could decide what happened with my money and my property.
I could not run my parents’ marriage.
The lease was for eighteen months.
Their rent was well below what I could have charged on the open market.
But it was enough to cover part of the property expenses and, more
importantly, establish a clear relationship.
They were tenants.
I was the owner.
Repairs were handled in writing.
Rent had a due date.
No more vague family accounting.
The first month, Mom handed me a check and looked offended.
“This feels ridiculous.”
“Why?”
“Paying my son rent.”
“You paid a bank for years.”
“That was different.”
“How?”
She could not answer.
I deposited the check.
Emily did not speak to me for three months.
Then she called on my birthday.
I almost did not answer.
“Happy birthday.”
She said.
“Thank you.”
“Are you doing dinner?”
“Yes.”
“With Mom and Dad?”
“No.”
A pause.
“Can I come?”
I was surprised.
“Why?”
“Because I’m your sister.”
“That hasn’t always been a convincing argument.”
“I know.”
Her voice was quieter.
“I owe you an apology.”
We met for coffee first.
Emily arrived without the performance I was used to.
No stories about hotels.
No comments about clothes.
She sat across from me.
“The five-dollar thing was mean.”
“Yes.”
“I thought it was funny.”
“I know.”
“Mom told me before dinner.”
That surprised me.
“Told you what?”
“That she was putting five dollars in the card.”
“You knew?”
“Yes.”
“And you thought it was funny?”
“At the time.”
I waited.
Emily looked down.
“I liked being the successful one.”
There it was.
A sentence more valuable than a hundred excuses.
“You were successful.”
I said.
“Sometimes.”
She shook her head.
“I was spending like success was a costume.”
I said nothing.
“Spain went on a credit card.”
She continued.
“The suite was discounted because a friend worked for the hotel group.”
“The designer stuff?”
“Some real.”
She smiled sadly.
“Some resale.”
“Why did you care whether I looked cheap?”
“Because if you were careful and doing well, then what did that make
me?”
I leaned back.
“That sounds like a question for you.”
“It was.”
She nodded.
“I just didn’t ask it until everything fell apart.”
Emily had not become poor.
Her life had simply been more fragile than her social media suggested.
Credit-card balances.
Personal loans.
A business idea that never became a business.
Money from Mom and Dad.
Money borrowed against the house.
She had not caused every financial problem.
Dad’s unemployment mattered.
My parents’ spending mattered.
Their refinancing decisions mattered.
But Emily had benefited from a family system that protected her from
limits.
Just as I had been harmed by it.
“I’m sorry.”
She said.
“For the dinner.”
“For taking money from Mom and Dad when I knew they were struggling.”
“For acting like your caution meant you were boring.”
Then she smiled.
“And for saying you didn’t own clothes good enough for Spain.”
I looked down at my shirt.
It was new.
She laughed.
“Okay, that one might have helped.”
I laughed too.
She came to dinner.
She brought me a birthday card.
Inside was a five-dollar bill.
I stared at it.
Emily immediately said:
“Keep reading.”
Under the bill, she had written:
I owe you one real birthday gift and approximately fifteen years of
better behavior. This five is only here because I deserve the anxiety on
your face.
I laughed.
Actually laughed.
Then she handed me a small box.
Inside was a watch.
Nothing extravagant.
On the back, she had engraved one word.
ENOUGH.
I looked at her.
“How did you know?”
“Mom saw the notebook.”
Of course she had.
That bothered me.
Then I decided not to ruin the moment.
“Thank you.”
I said.
“You’re welcome.”
My relationship with my parents took longer to repair.
Dad adapted to the new arrangement better than Mom.
He found steady work six months after the sale.
Not the salary he once earned.
Enough.
He started contributing to savings again.
Mom took a part-time administrative job at a dental office.
She had not worked outside the home in years.
At first, she complained constantly.
Then something strange happened.
She liked it.
She liked having coworkers.
She liked getting paid.
She liked buying Christmas gifts with money she had earned herself.
One afternoon, she called me.
“I understand something now.”
“What?”
“Why you got so angry when we treated your promotion like an ATM.”
I was silent.
She continued.
“I got a small raise.”
“Congratulations.”
“Thank you.”
She laughed.
“I called your father first because I wanted him to be proud.”
“Was he?”
“Yes.”
“And then?”
“I remembered when you told me about your promotion.”
I knew exactly what she meant.
Oh, that’s nice. Listen, we need to ask you something.
“I’m sorry.”
She said.
“I made your achievement about what it could do for us.”
My throat tightened.
“Yes.”
“I should have said I was proud of you.”
“Thank you.”
“I am.”
That apology mattered more than the money.
At the end of the eighteen-month lease, my parents had a decision.
Renew.
Or move.
Dad surprised me.
“We should move.”
Mom looked devastated.
But Dad had done the numbers.
The house was too large.
Taxes were high.
Maintenance was expensive.
Even with below-market rent, they were spending more than they needed.
They found a two-bedroom townhouse twenty minutes away.
Smaller.
Newer.
No giant yard.
No old roof.
Mom cried while packing.
So did I.
Emily came to help.
We found boxes of childhood photographs.
School projects.
Dad’s old baseball glove.
A ceramic bowl I made in sixth grade that Mom had somehow preserved
despite it being objectively terrible.
On the final afternoon, the four of us stood in the empty living room.
Mom touched the wall.
“I thought losing this house meant losing the family.”
I looked around.
“It didn’t.”
“No.”
She looked at me.
“I think trying to keep it almost did.”
Dad put his arm around her.
Emily picked up the last box.
“Can we get sentimental after we move this? It’s heavy.”
Mom laughed through her tears.
They left.
I stood alone in the house.
For the first time since buying it, it was truly mine to decide what to
do with.
I could have moved in.
I did not want to.
I could have sold it.
The market was favorable.
Instead, after reviewing the numbers, I rented it to a family with two
children.
At market rent.
Through a professional property manager.
No family exceptions.
No emotional accounting.
The first rent payment landed in my account on a Tuesday.
I stared at it for a few seconds.
Then closed the banking app.
It did not feel like revenge.
It felt like an asset being an asset.
That was all.
Years earlier, my family had treated money as a measure of love.
If I gave, I cared.
If I refused, I was selfish.
If Emily spent, she was enjoying life.
If I saved, I was boring.
If my parents needed help, my higher income became a moral obligation.
The rules were never really about money.
They were about roles.
Emily was the exciting child.
I was the reliable one.
Reliable meant available.
Available meant responsible.
Responsible eventually meant financially responsible for everyone.
The five-dollar birthday card was funny to them because it fit the role
they had assigned me.
Ryan is so careful with money.
Ryan never has fun.
Ryan can take a joke.
Ryan will pay anyway.
And I did.
That night, I paid $1,126.43 for the privilege of being laughed at.
I do not regret paying the bill.
Not anymore.
It became the last payment I made without asking myself whether I
actually wanted to.
That distinction changed my life.
Three years after buying the house, I received another promotion.
This time, I did not tell my family immediately.
Old habits.
Emily found out through LinkedIn.
She called.
“You got promoted?”
“Yes.”
“You jerk.”
I laughed.
“Congratulations.”
“Thank you.”
“Are you celebrating?”
“I was thinking dinner.”
“I’m paying.”
“No.”
“Yes.”
“Emily.”
“Ryan.”
“I can afford dinner.”
“So can I.”
She paused.
“And I would like to buy my brother dinner because I’m proud of him.”
That silenced me.
“Okay.”
I said.
We went to a small steakhouse.
Mom and Dad joined us.
When the check arrived, I automatically reached for it.
Emily slapped my hand away.
“Absolutely not.”
Dad laughed.
Mom said:
“Let her.”
I did.
Nobody made a joke about my clothes.
Nobody asked about my salary.
Nobody mentioned the mortgage.
At dessert, Mom handed me a card.
I looked at her suspiciously.
She laughed.
“It’s not five dollars.”
I opened it.
There was no money.
Just a handwritten note.
Ryan,
We spent too many years confusing your strength with an obligation to
carry us.
You were generous when you did not have to be.
We became entitled to that generosity.
We are sorry.
We are proud of the life you built.
Not because it can rescue us.
Because it is yours.
Love, Mom and Dad.
I read it twice.
Then folded it carefully.
“That’s better than five dollars.”
I said.
Dad smiled.
“Inflation.”
We laughed.
This time, I laughed too.
Not because the past had become harmless.
It had not.
My parents had pressured me.
They had used guilt.
They had favored Emily in ways that hurt both of us.
They had borrowed against their house without a sustainable plan.
I had participated too.
Every time I said yes when I meant no, I helped teach them that asking
would work.
That did not make their behavior my fault.
It did mean I had a role in changing what happened next.
I stopped trying to make boundaries feel painless to everyone.
Sometimes they hurt.
Sometimes Mom cried.
Sometimes Dad got angry.
Sometimes Emily thought I was judging her.
Sometimes I felt guilty.
A boundary can be correct and still feel terrible.
That was something nobody had taught me.
The notebook with ENOUGH written across the first page still sits in my
desk.
The number beneath it is still there.
$63,840.
I never updated it.
I could have added more.
The birthday dinner.
Legal fees.
Inspection costs.
The time I spent sorting through records.
But eventually, counting stopped being useful.
The number had already done its job.
It showed me that a pattern I kept calling temporary had lasted years.
That is what records can do.
Memory says:
It wasn’t that often.
A spreadsheet says:
Here are the dates.
Guilt says:
They need you.
A bank statement says:
You helped last month too.
Family mythology says:
Emily pays her own way.
A HELOC statement says:
$12,000.
$7,500.
$4,000.
Facts do not decide what you should do.
But they can make it harder to lie to yourself about what has been
happening.
People sometimes ask whether I bought my parents’ house to teach them a
lesson.
No.
If I had wanted to teach them a lesson, I would have let the foreclosure
process continue and watched from a distance.
I bought the house because, after professional advice and independent
review, it made financial sense for me and provided them with a workable
exit from a dangerous situation.
But I did it on terms I could live with.
That was the difference.
I did not secretly seize anything.
I did not manipulate the lender.
I did not pretend paying arrears gave me ownership.
My parents chose to sell.
They had independent advice.
They received the equity that remained after debts and costs.
I received the property I paid for.
Then we put our family relationship somewhere it had rarely been before.
Outside the transaction.
That separation saved more than the house.
It gave us a chance to rebuild without every expression of love carrying
a dollar amount.
Dad can call me now and say:
“I miss you.”
Without adding:
“By the way, the car needs tires.”
Mom can congratulate me without calculating what my promotion means for
her mortgage.
Emily can tell me about a vacation without using it to prove she is
winning.
And I can help when I choose.
I still help.
That surprises people.
Boundaries did not turn me into someone who never gives.
Last winter, Dad’s furnace failed.
He had enough savings to replace it.
I knew that.
I also knew the repair was expensive.
So I offered to cover dinner for my parents for a week while contractors
were in and out.
Mom said:
“You don’t have to.”
“I know.”
That was exactly why the offer felt good.
I did not have to.
I wanted to.
There is a world of difference between those two sentences.
On my thirty-second birthday, I took the old wrinkled five-dollar bill
out of the card where I had kept it.
Yes.
I had kept it.
For five years.
Not because it was sentimental.
Because it reminded me of the moment I finally saw the joke clearly.
I put it in a frame beside the engraved watch Emily gave me.
Underneath, I added a small label.
ENOUGH.
When Emily saw it, she laughed.
“That is incredibly dramatic.”
“You helped create it.”
“Fair.”
Mom rolled her eyes.
Dad asked whether the five dollars had appreciated.
I told him it had produced an excellent return.
Not financially.
Personally.
That birthday gift had cost them five dollars.
The lesson it triggered was worth far more.
It taught me that generosity without boundaries eventually becomes
expectation.
Expectation without gratitude becomes entitlement.
And entitlement protected by guilt can make love feel like a bill that
never stops arriving.
I do not live that way anymore.
My family does not either.
Not perfectly.
We still argue.
Mom still occasionally offers opinions nobody requested.
Dad still believes every home repair should begin with him watching six
online videos.
Emily still buys shoes I consider ridiculous.
I am still careful with money.
Only now nobody uses careful as an insult.
They understand what it built.
Security.
Choice.
The ability to say yes without fear.
And, more importantly, the ability to say no without believing I have
forfeited my place in the family.
The night Mom told me I might not deserve to be part of the family, I
thought something had broken forever.
Something did break.
Just not what she intended.
The belief that belonging had to be purchased.
I never repaired that belief.
I replaced it.
Family is not the people who can invoice you most successfully.
Family is not a mortgage payment.
It is not a car loan.
It is not a birthday check.
It is not a five-dollar joke.
It is the people who can hear no and still call you son.
Brother.
Dad.
Mom.
The people who can apologize without demanding that the apology erase
what happened.
The people who learn.
The people who let you learn too.
At twenty-seven, I sat at a white-tablecloth restaurant while everyone
laughed at the crumpled five-dollar bill in front of me.
Then they handed me the check.
I paid it.
Almost a year later, they handed me a much larger bill.
A house on the edge of foreclosure.
This time, I did not simply pay.
I asked questions.
I got records.
I sought advice.
I made sure that if I took financial risk, I also had lawful control
over the asset.
And when Mom cried with relief after I said, “I’ll take care of it,” she
thought the old Ryan had returned.
He had not.
The old Ryan believed saving everyone else was the price of being loved.
The man who bought that house knew better.
I did take care of it.
I took care of the mortgage problem.
I took care of my finances.
May you like
I took care of my future.
And for the first time in years, I took care of myself too.